Agenda-setting intelligence, analysis and advice for the global fashion community.
Agenda-setting intelligence, analysis and advice for the global fashion community.
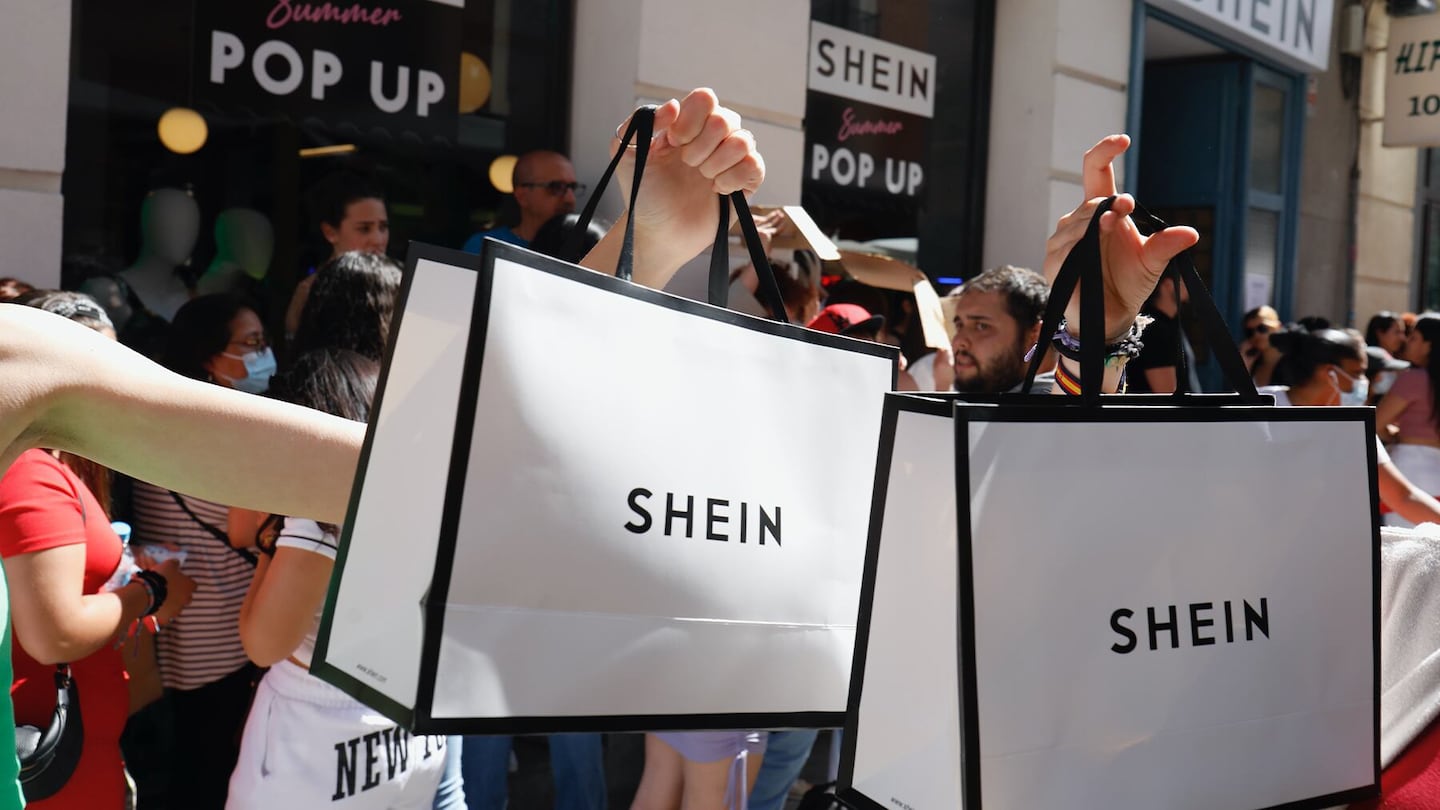
For everyone else, the journey has been costly — starting with the company itself. The Singapore-based online retailer priced the Hong Kong initial public offering at HK$48.56 ($6.19) per share on Thursday, valuing it at just over $26 billion. That’s about a quarter of the $100 billion it was worth at its private-market peak four years ago.
Some existing shareholders are being cushioned from the collapse in value, but that hardly makes them winners. Shein had agreed to pay as much as $3.5 billion to pre-IPO investors. Their purchases included protections against a steep markdown. As a result, the hefty payout could amount to roughly double the $1.7 billion raised in the IPO.
There is, however, one group with reason to celebrate: the vast network of suppliers in southern China that powers the retail juggernaut. Concentrated in the southern part of Guangzhou, thousands of small factories, making mostly clothing, are the muscle behind the ultra-fast-fashion model. A close-knit, tightly integrated supply chain located in a compact area allows Shein to identify trends, place tiny initial orders and get them ready for delivery within two weeks. That is especially true in women’s fashion, the category it still dominates, despite intense competition from PDD Holdings Inc.’s Temu.
The irony is that this is the network that the fashion giant had once tried to play down by moving to Singapore and rebranding as a global company to appeal to Western investors. That strategy failed due to fierce US opposition, as well as an inability to reproduce in countries like Brazil and Turkey the speed, flexibility and low costs of its primary production base.
ADVERTISEMENT
The IPO should bind those suppliers even more closely to Shein. The company plans to devote 40 percent of the proceeds to technology, according to the prospectus, including investments designed to improve the manufacturing network at the heart of the business.
Shein’s next act will only deepen the relationship. With growth in the US and Europe, two of its biggest regions, slowing due to greater protectionism and competition, the company is telling investors that future expansion will come from offering the Guangzhou supplier network to other brands. The approach calls for acquiring labels and plugging them into the same group of factories or providing those services to other firms.
But turning its manufacturing prowess into someone else’s growth engine may be harder than it sounds. The retailer launched a fashion incubator for budding designers in 2021. Two years later, it evolved into the Xcelerator program, which offers product fulfilment, production support and access to the sales platform. The results have been modest, accounting for no more than 1 percent of sales last year. It’s hard to see how the scheme could move the needle.
Buying brands may be a better bet. An established label comes with something that Shein’s factories can’t make: recognition and a ready-made customer base. But this strategy also comes with caveats. The deal to purchase American millennial clothing brand Everlane, announced in May and subject to a US security review, looks like an awkward fit.
The US label built its fanbase on supply-chain transparency and sustainable production, attributes that clash with an ultra-fast-fashion ethos. Plugging it into the same manufacturing machine risks eroding the very qualities that made the brand worth buying in the first place. Shein should go after acquisition targets that better match its production model.
The subdued response to the IPO suggests investors aren’t totally convinced that Shein has found its next growth engine. At this price, the company trades at 13 times trailing earnings, a considerable discount to Zara owner Inditex SA, Swedish retailer Hennes & Mauritz AB and Japan’s Fast Retailing Co. The retailer has the difficult task of proving that the manufacturing system that transformed fashion can do so again.
The listing has already delivered one verdict. Shein spent years recasting itself as a global company, only to discover that its greatest strength remains unmistakably Chinese. Its valuation may have shrunk, but the value of the manufacturing ecosystem behind it has never been clearer.
ADVERTISEMENT
By Juliana Liu
Learn more:
Shein’s IPO Won’t Mask Its Sustainability Challenges
The company has tried to address ESG concerns that have triggered regulatory investigations and fines in several countries, but many of those challenges remain and could weigh it down even after its market debut.
Loading recommended reads…
The Jared, Kay and Zales owner raised its outlook for the second time this year as demand for jewellery remains resilient even as shoppers pull back on spending elsewhere.
As AI makes digital imagery even easier to fake, BoF's Diana Pearl and Marc Bain join Sheena Butler-Young on The Debrief to unpack why some luxury brands are betting on real artists and handmade craft to win back customers who feel alienated by a fashion industry built for the screen.
Prize alum Rachel Scott of Diotima is nominated for Womenswear Designer of the Year again, while 2013 winners Dao-Yi Chow and Maxwell Osborne of Public School are nominated for Menswear Designer of the Year.
An industry temperature check in Geneva showed executives concerned about component suppliers as the polarisation of the Swiss watchmaking sector deepens.